Independent property claim appraisal · Commonwealth-wide
Virginia Insurance Appraiser for claims that came up short
When your insurer accepts the claim but the payment won’t cover the repair, Virginia Insurance Appraiser builds an independent, line-by-line valuation and carries it through the appraisal process written into your policy.
- Named appraiser or neutral umpire
- Pricing for your Virginia ZIP code
- Homes, condos, HOAs and businesses
- 133Virginia localities served
- 95counties, plus 38 independent cities
- 12appraisal & estimating services
- 2 of 3signatures make an award binding
The short version
What a Virginia Insurance Appraiser does, and doesn’t do
Most short claims aren’t denials. They’re estimates that missed something: two slopes instead of five, plaster priced as drywall, a floor that can’t be matched, a crane left off a tree job. Virginia Insurance Appraiser works on that gap between “covered” and “paid in full.”
- We value the loss from scratch. Our own inspection and measurements, never an edited copy of the insurer’s estimate.
- We build numbers that survive scrutiny. An inflated estimate loses credibility with an umpire. A documented one moves the award.
- We tell you when appraisal is the wrong tool. Denials, coverage fights and looming suit deadlines belong with a Virginia attorney.
Appraisal & estimating
Services from Virginia Insurance Appraiser
Twelve services, one goal: a valuation of your loss that holds up. Start with an estimate review, or bring us in after appraisal has been demanded.
 Service 01
Appraisal Clause Representation
Named as your appraiser after a written demand, we value the loss and work the panel to a signed award.Read more Service 02
Homeowners Insurance Appraisal
Independent valuation for houses, townhomes and condos when the carrier’s check won’t cover the repair.Read more Service 03
Commercial & HOA Claim Appraisal
Appraisal for retail, office, warehouse, church, apartment and condo-association losses with large scopes.Read more Service 04
Roof & Hail Damage Appraisal
Measured, slope-by-slope valuation of hail and roof damage, including matching and code items.Read more Service 05
Wind & Tornado Damage Appraisal
Valuation of derecho, squall-line and tornado damage to roofs, siding, framing and outbuildings.Read more Service 06
Hurricane & Nor’easter Appraisal
Wind and wind-driven-rain valuation for Hampton Roads and Eastern Shore storm losses.Read more Service 07
Water Damage Claim Appraisal
Burst pipes, appliance failures and roof leaks, valued with drying, tear-out and matching included.Read more Service 08
Fire & Smoke Damage Appraisal
Structure, smoke, soot and contents valuation for kitchen fires, lightning strikes and total losses.Read more Service 09
Fallen Tree & Ice Storm Appraisal
Tree strikes and ice-load failures valued with crane work, framing repair and debris-removal limits.Read more Service 10
Historic Home Claim Appraisal
Plaster, heart pine, slate and old-growth trim valued at the real cost of like-kind repair.Read more Service 11
Insurance Estimate Review
A line-by-line review of the carrier’s estimate showing exactly what’s missing and what it’s worth.Read more Service 12
Umpire Selection & Services
Neutral umpire work, plus help choosing a qualified umpire when the two appraisers can’t agree.Read moreHonest triage
When to call a Virginia Insurance Appraiser, and when not to
Appraisal usually fits
- Coverage is accepted, but the amount is disputed
- Repair-versus-replace disagreements on roofs and siding
- Matching problems with discontinued materials
- Missing trades, code items, crane work or overhead and profit
Appraisal usually doesn’t
- The claim was denied outright
- The dispute is about what the policy covers
- A suit deadline is close and needs an attorney
- The gap is too small to justify the fees
The process
Seven steps from short check to signed award
The appraisal clause turns an open-ended argument into a defined procedure. Here is how Virginia Insurance Appraiser moves a file from the first call to a binding number.
- 1
Spot the disagreement
Coverage is accepted, but the insurer’s figure and the real repair cost are far apart.
- 2
Build the file
Gather the policy, the full estimate, photos, a contractor’s estimate and the correspondence.
- 3
Make the written demand
Either side demands appraisal in writing, citing the policy’s appraisal condition.
- 4
Name the appraisers
Each side names a competent, disinterested appraiser, often within 20 days.
- 5
Select an umpire
The two appraisers agree on a neutral umpire, or a court can be asked to appoint one.
- 6
Work the differences
The appraisers compare scopes and prices and resolve as many items as they can.
- 7
Sign the award
Any two of the three sign. The award sets the amount of loss, and payment follows under the policy.
Quick check
Is the gap big enough for appraisal?
Type in the two numbers you already have. If the difference is large, a conversation with a Virginia Insurance Appraiser makes sense. If it’s small, a documented supplement may close it faster and cheaper.
The full claim gap & fee estimator adds appraiser and umpire fees so you can see a realistic net figure. Example figures are illustrative.
Two-number gap check
Nothing is storedFive claim climates
Virginia’s regions don’t file the same claims
Hurricanes in Norfolk, flash floods in Arlington, ice in Charlottesville, hail in Roanoke. A Virginia Insurance Appraiser has to know how each region’s weather shows up on a roof and in an estimate.
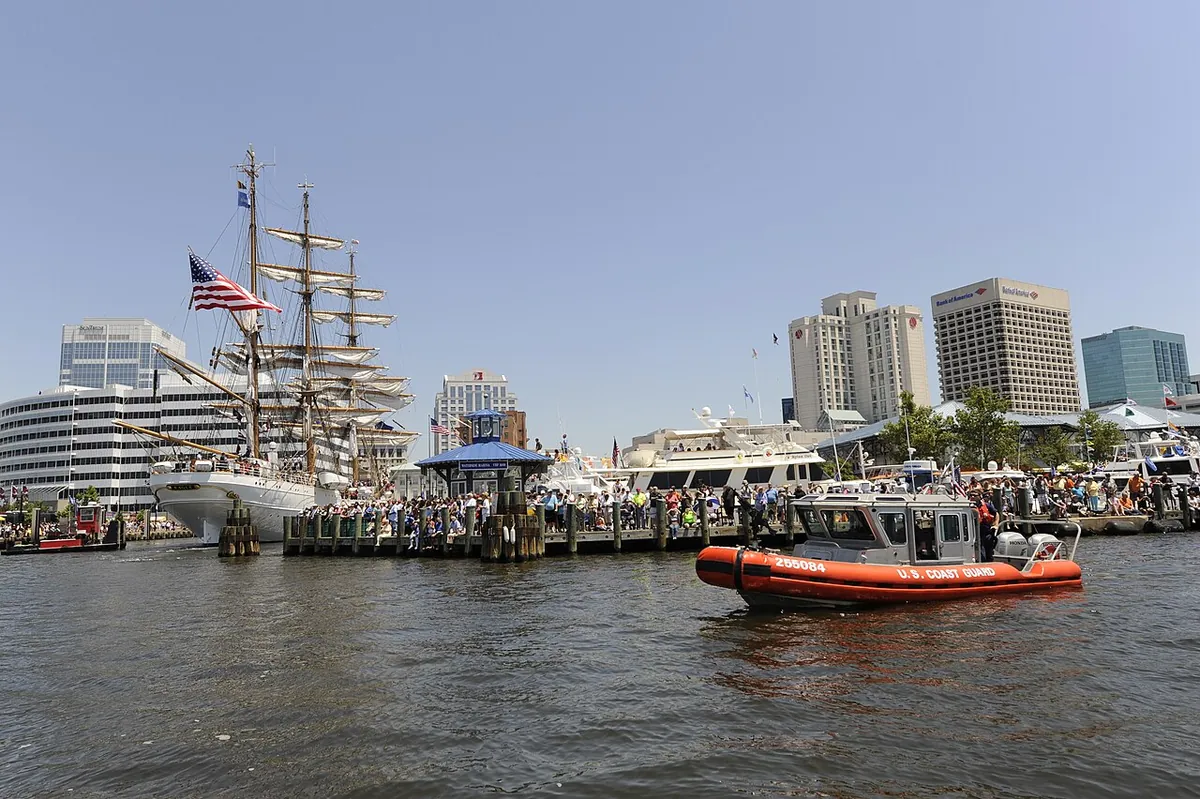
Hampton Roads & Eastern Shore
- Hurricanes
- Nor’easters
- Wind-driven rain
- Condo losses
Named-storm deductibles, wind-versus-flood questions and crawlspace homes define claims from Virginia Beach and Norfolk to Hampton, Suffolk and the Eastern Shore.
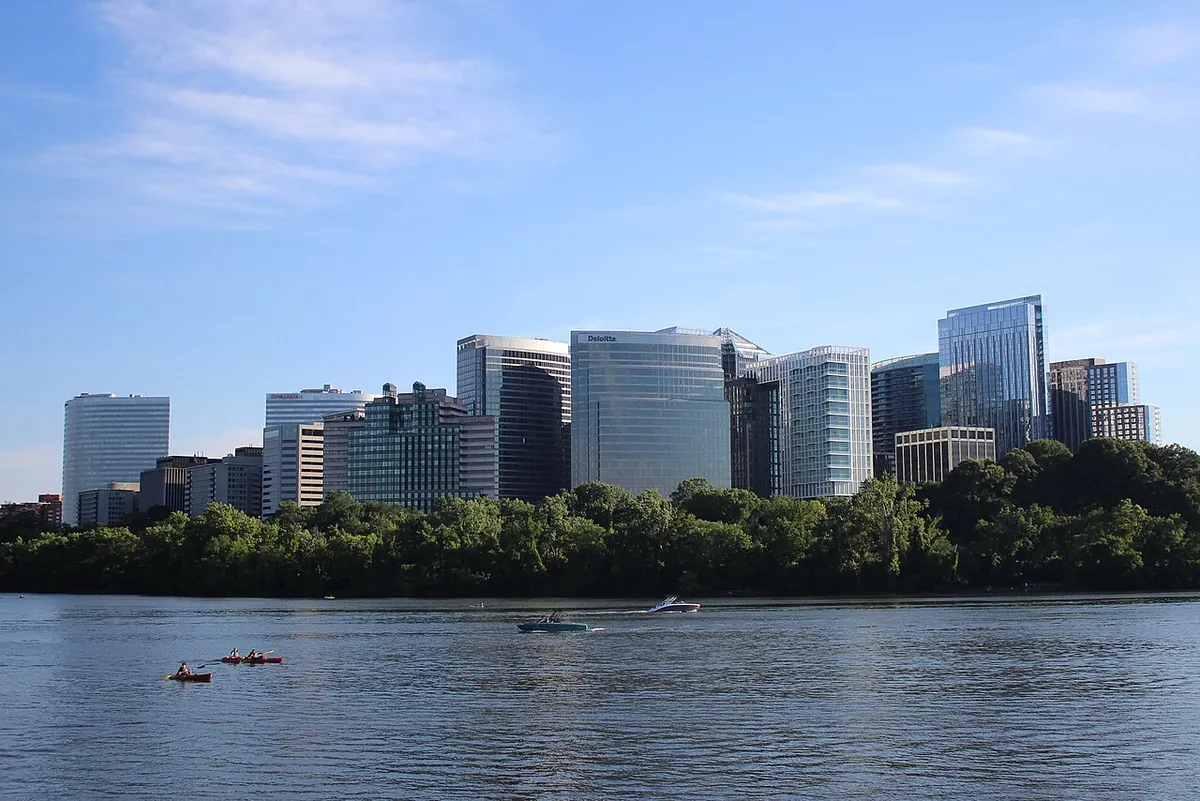
Northern Virginia
- Flash flooding
- Derechos
- Fallen trees
- High-rise water losses
Arlington, Alexandria, Fairfax, Loudoun and Prince William bring high-dollar finishes, finished basements, condo towers and the state’s highest construction prices.
Richmond & Central Virginia
- Tree strikes
- Hail
- Ice
- Historic rowhouses
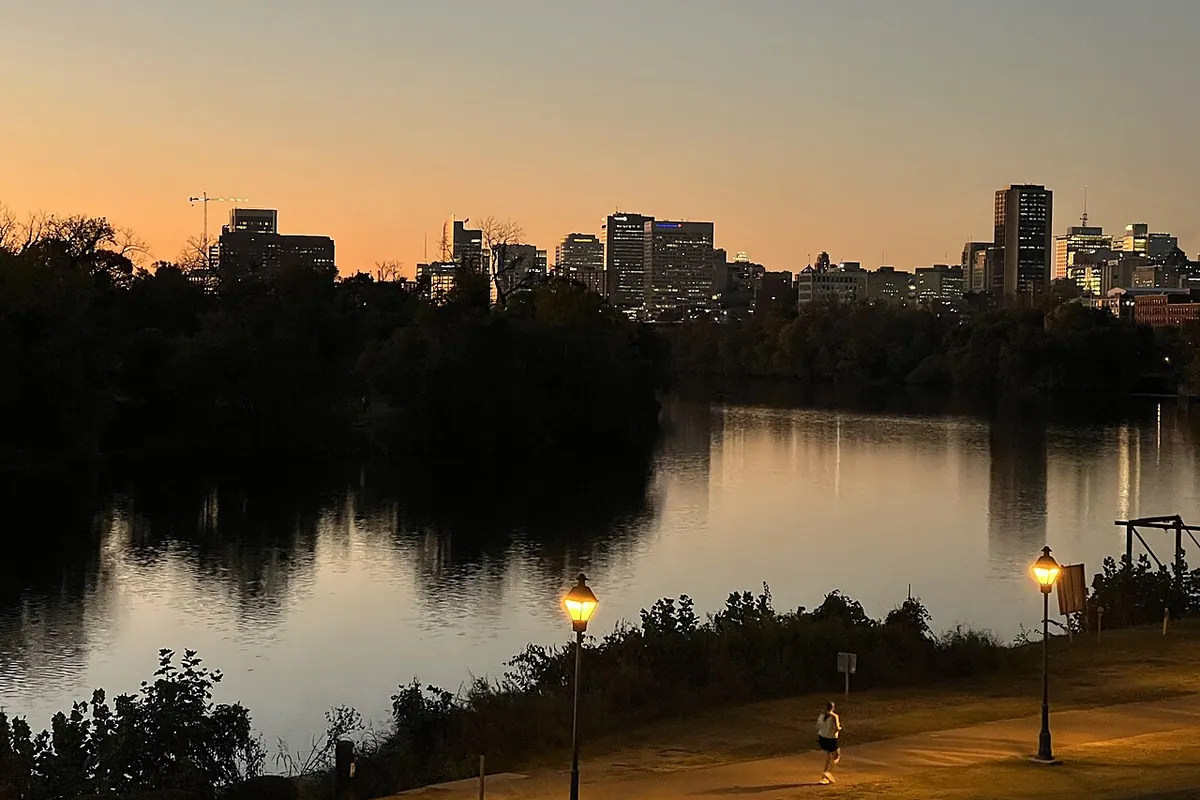
Richmond’s rowhouses, Fredericksburg’s historic downtown and fast-growing suburbs in Henrico, Chesterfield and Stafford see thunderstorms, hail and ice under a heavy tree canopy.
Shenandoah Valley & Blue Ridge
- Hail
- Ice storms
- Frozen pipes
- Steep roofs
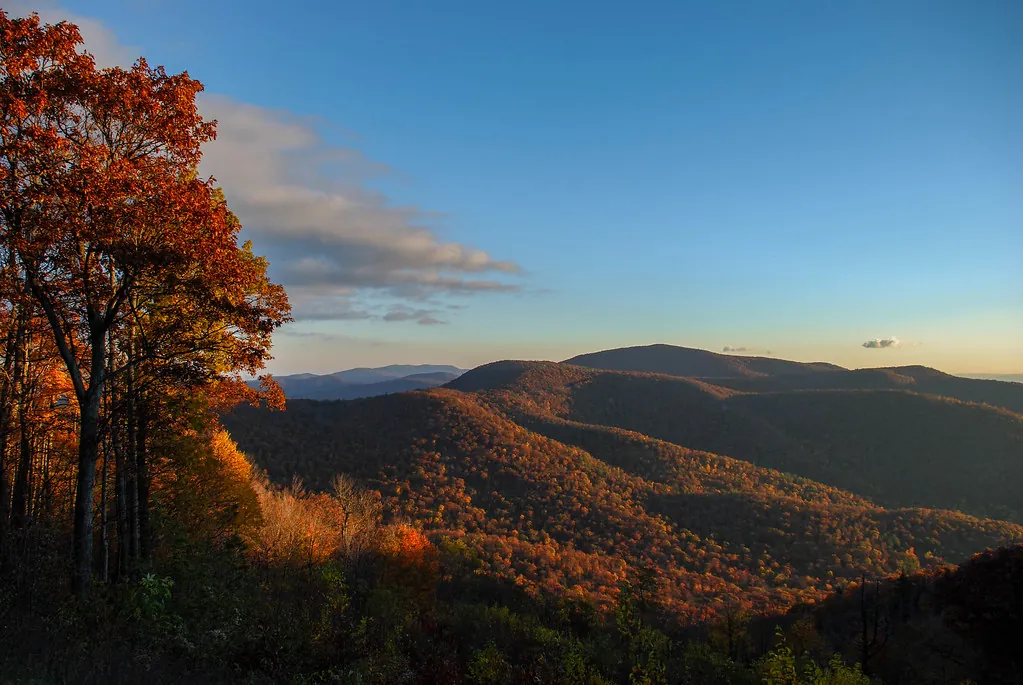
Charlottesville, Harrisonburg, Staunton and Winchester sit in hail country, with winter ice, slate roofs on older homes and steep lots that raise labor costs.
Roanoke, Southside & Southwest
- Flash flooding
- Tornadoes
- Hail
- Ice
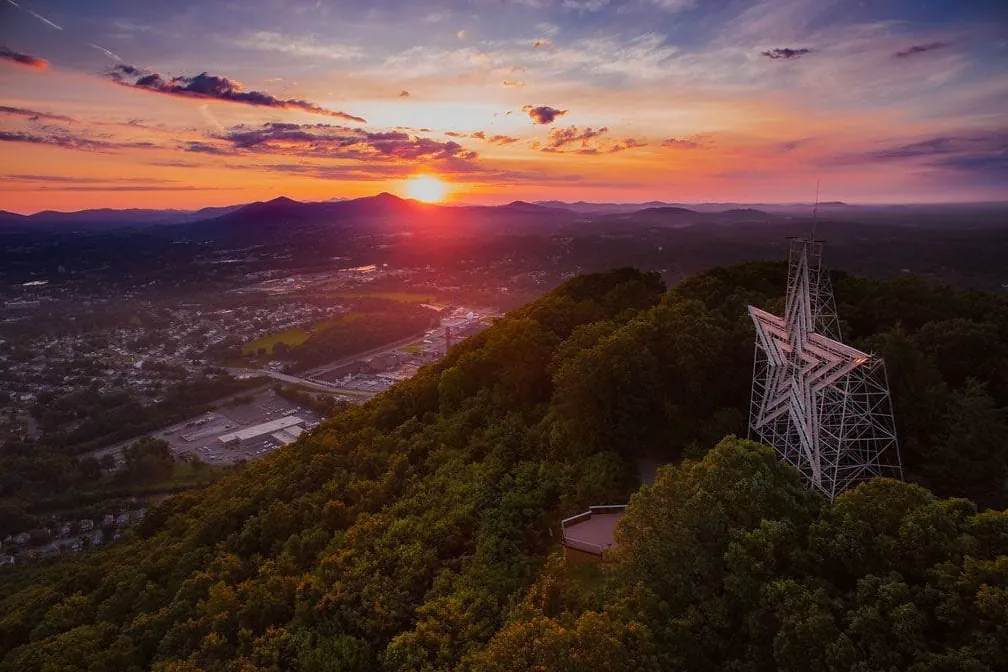
From Roanoke and Lynchburg to Danville and the coalfields, claims follow mountain flash floods, spring tornadoes and the kind of hail that strips old roofs.
Local knowledge
Where Virginia Insurance Appraiser works most
We take files in every county and independent city. These twelve localities each have their own page with local storm history and housing notes.
 Virginia BeachHampton RoadsNorfolkHampton Roads
 ChesapeakeHampton Roads
 Newport NewsHampton Roads (Peninsula)RichmondCentral VirginiaArlingtonNorthern Virginia
 AlexandriaNorthern VirginiaFairfax CountyNorthern Virginia
 FredericksburgNorthern Neck & Rappahannock
 CharlottesvilleCentral Virginia & PiedmontRoanokeRoanoke Valley & Southwest
 LynchburgCentral Virginia & Southside
Virginia ground rules
Four facts every Virginia policyholder should know
A Virginia Insurance Appraiser isn’t a lawyer, but these basics shape every claim we see. They’re general information, not legal advice.
Bureau of Insurance
Part of the State Corporation Commission. It licenses insurers, agents and public adjusters and takes consumer complaints.
VPIA, the FAIR Plan
The Virginia Property Insurance Association offers basic property coverage to owners who can’t find it in the regular market.
Va. Code § 38.2-209
Lets a court award costs and attorney’s fees in certain cases where an insurer refused to pay in bad faith. That’s a legal question, outside appraisal.
Commonly two years
Virginia’s standard fire policy provisions commonly allow two years from the loss to file suit. Your policy controls, and appraisal may not pause it.
Free & private
Seven free tools from Virginia Insurance Appraiser
Run the numbers before you pick up the phone. Every calculator runs in your browser, and nothing you enter is stored or sent.
EstimatorClaim Gap & Fee Estimator
Measure the disputed amount, test where an award might land and subtract realistic appraisal fees.Read moreCalculatorHoldback Recovery Calculator
Split a claim into the first ACV check, the depreciation held back and the total after repairs.Read moreCalculatorRoof Pitch & Squares Checker
Turn a footprint into true roof squares with pitch and waste, then check the estimate’s numbers.Read more Converter
Hurricane & Wind Deductible Converter
Turn a percentage hurricane, named-storm or wind deductible into dollars and see what a claim pays.Read more Planner
Claim Clock & Calendar Builder
Map notice, proof-of-loss, holdback and suit dates from your date of loss, then export an .ics file.Read moreChecklistAppraisal Readiness Scorecard
Answer 12 yes/no questions to score your claim file and get a to-do list before demanding appraisal.Read moreCalculatorFallen Tree Claim Splitter
Split a tree claim into dwelling repair, capped removal and what you pay, using your policy’s limits.Read moreChoosing help
Appraiser, public adjuster or attorney?
Each solves a different problem. Virginia Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
| Question | Virginia Insurance Appraiser | Public adjuster | Attorney |
|---|---|---|---|
| Main job | Value the amount of loss | Handle and negotiate the claim | Legal disputes and lawsuits |
| Best stage | Coverage accepted, amount disputed | Early, from first notice | Denials, bad faith, deadlines |
| Result | Binding award (2 of 3 signatures) | Negotiated settlement | Settlement or judgment |
| Decides coverage? | No | No | Argues it in court |
FAQ
Questions people ask a Virginia Insurance Appraiser
Straight answers about how appraisal works, what it costs and when it’s the wrong move.
What does a Virginia Insurance Appraiser do?
We value property damage when you and your insurer agree the loss is covered but disagree about what it costs. As your named appraiser, we inspect, build an independent line-item estimate, work with the insurer’s appraiser and present open items to a neutral umpire if needed.
How is that different from a public adjuster?
Public adjusters are licensed by the Virginia Bureau of Insurance to handle and negotiate whole claims. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When is it worth calling a Virginia Insurance Appraiser?
When coverage has been accepted, you have the insurer’s estimate, and the gap between it and a qualified contractor’s number is meaningful, often more than about 10% or several thousand dollars.
Is an appraisal award binding?
On the amount of loss, yes, once two of the three panel members sign. That’s why we build the file carefully before anyone demands appraisal.
What does it cost?
Each side pays its own appraiser and usually half of the umpire’s fee. We put our fee in writing before any work begins, and the first review is free.
Which parts of Virginia do you serve?
All of it: 95 counties and 38 independent cities, with regular work in Hampton Roads, Northern Virginia, Richmond, Charlottesville, Roanoke and Lynchburg.
Guides
Read this before you demand appraisal
Practical guides from Virginia Insurance Appraiser on policy language, documentation and the rules that apply in Virginia.
Guide · 7 min readReading a Virginia Appraisal Clause Line by Line
What each sentence in a typical appraisal condition means, and the traps hidden in the short paragraph.Read moreGuide · 6 min readInsurance Bad Faith in Virginia: Where Appraisal Fits
A cautious overview of Virginia’s bad-faith and unfair-claims statutes, and why they’re separate from appraisal.Read moreGuide · 6 min readStorm Damage Documentation That Holds Up in Appraisal
What to photograph, measure and save after a derecho, tree strike or hailstorm so your claim holds up later.Read moreBefore you sign off
The best time to check the numbers is before you accept them
A short review now can keep you from settling for a payment that won’t cover the repair.
Start with a conversation
Talk to a Virginia Insurance Appraiser about your claim
Tell us what happened and what the insurer offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing. No pressure, no obligation.
- Call or text+1 (844) 537-1427
- Emailinfo@virginiainsuranceappraiser.com
- HoursMon–Fri, 8am–6pm ET
- CoverageAll 133 Virginia localities